Aimdyaflaepliasoemni
Our story in behavioral finance and everyday self control
Helping you close the gap between money intentions and daily decisions
Aimdyaflaepliasoemni exists for people who are tired of knowing better yet doing the opposite
with money. We explore how self control problems show up in your saving,
spending, and debt repayment, then help you design practical ways to stick with
your plans when motivation is low and temptations are loud.
We started Aimdyaflaepliasoemni after seeing the same pattern repeat in friends, colleagues, and clients across India. They were not short on information; they were short on structures that respected real life. So we built an approach that begins with your habits, your cultural context, and your daily pressures, then layers in behavioral tools like commitment devices, prompts, and friction. We keep the focus on what you can actually do this week, not on abstract ideals.
On this page, we share the story behind Aimdyaflaepliasoemni, the ideas that guide our work, and the values we refuse to compromise on. You will see how we think about self control, why we care so much about the psychology of saving and spending, and how we blend evidence from behavioral economics with the lived reality of managing money in India. Our hope is that you recognise your own struggles in these stories and feel less alone, more understood, and more prepared to experiment with new ways of relating to your finances.
You know that strange gap between what you promise yourself about money and what actually happens when your salary arrives? You plan to save, spend less on impulse buys, and finally clear that old loan, yet the month slips by and the numbers barely move. At Aimdyaflaepliasoemni, we live inside that gap. We focus on the everyday self control problems that quietly shape saving, spending, and debt repayment, and we treat them as design issues, not character flaws. When we look at your financial life, we see habits, triggers, and systems that can be gently rewired. We draw on behavioral finance, psychology, and simple routines to help you build plans that are realistic on a tired Tuesday night, not only on a hopeful Sunday afternoon. Our work is less about heroic willpower and more about arranging your environment so the sensible choice becomes the easy one. Over time, small, repeatable decisions start lining up with your long term intentions, and your money story feels less chaotic and more deliberate.
Our journey so far
How a handful of scribbled notes grew into a focused practice around money and self control
Aimdyaflaepliasoemni began as a collection of late night notes after yet another conversation with friends who were frustrated with their own money habits. They were earning well but could not understand why saving felt so hard and debt repayment kept slipping. Our founder started reading deeply on behavioral economics, self control, and the way attention and emotion affect financial choices. Those notes slowly turned into simple experiments: automatic transfers set just after salary credit, small rules around online shopping, and clearer repayment reminders. The early results were modest but meaningful, and the idea for a focused practice around self control in personal finance took root.
Over the next few years, these experiments moved from personal circles into more structured one to one conversations. We saw the same patterns across different cities and income levels in India: people understood the numbers, yet struggled to follow their own plans when life became hectic or stressful. We refined a method we now call the Gentle Guardrails Framework, which combines simple rules, pre commitments, and visual cues to support saving, spending, and debt repayment without harsh restrictions. During this time, we also began collaborating with counsellors and planners to make sure our approach stayed grounded and responsible.
As more people reached out, it became clear that we needed a dedicated space focused on behavioural aspects of money, separate from product sales or formal planning. Aimdyaflaepliasoemni was created as that space. We set up processes to protect client privacy, documented our approach in plain language, and designed tools that work well with popular payment and banking apps in India. The focus stayed on helping individuals understand their own patterns and test small, low pressure changes rather than chasing dramatic overnight shifts.
Today, Aimdyaflaepliasoemni continues to evolve through the real stories clients share with us. We keep refining our Gentle Guardrails Framework, adding new ways to handle digital temptations, seasonal spending, and the emotional weight of long term repayments. We remain careful about what we promise and always remind clients that results may vary. Our role is to offer structure, reflection, and tools so you can make steadier decisions that match your intentions, even when motivation dips.
Our values
These values keep us honest when we design tools for saving, spending, and debt repayment, especially when self control feels fragile or worn out.
We assume you already carry enough shame about money. Our first job is to listen
carefully, understand your pressures, and treat your story with respect. We speak
plainly, avoid judgement, and design changes that honour your responsibilities,
culture, and limits, so you feel safe enough to be honest about what really happens
with your money.
$
Evidence aware
Our ideas are grounded in behavioural research and real life observations, not in
bold promises. We explain why a tool might help with self control, what its limits
are, and where it may not fit your situation. We are transparent about uncertainties
and always remind you that results may vary, especially with complex financial and
emotional histories.
Money is deeply personal, and we treat your information with care. We use only what we need to understand your patterns, store it securely, and never share it without clear consent. You stay in control of what you disclose, and you can step back from any exercise that feels too intrusive or uncomfortable.
$
Long view
We care more about habits that last than about short bursts of perfect behaviour. That means designing saving, spending, and repayment routines you can keep up during busy weeks, family events, and tired evenings. We celebrate small, steady steps and keep adjusting the plan as your life changes, instead of chasing dramatic transformations.
$
Shared agency
We see our work with you as a partnership. You bring your history, instincts, and goals; we bring structure, reflection, and behavioural tools. Together we test changes, notice what works, and refine the plan. You always make the final call, and we respect your pace, your boundaries, and your right to change direction.
Our philosophy on self control and money habits
We built our philosophy around a simple observation: most people do not need more financial tips, they need help making the sensible choices feel natural when temptation is right in front of them. When we understand how attention, emotion, and habit loops shape saving, spending, and debt repayment, we can design small structures that quietly support self control instead of fighting against it. Our work blends behavioral finance research with practical money systems that can survive busy weeks, family obligations, and sudden expenses.
1
We treat money decisions as context driven, not purely logical. By mapping when and where you overspend or delay repayments, we can adjust cues and routines instead of blaming willpower.
2
We focus on making the first step tiny and concrete. A modest automatic transfer or a pre committed payment date often matters more than a grand long term target.
3
We use commitment tools carefully, such as scheduled transfers or spending rules, to help you protect future you from present you, while still keeping room for flexibility.
4
We respect emotion in money choices. Regret, guilt, and pride can be redirected into helpful rituals rather than ignored or pushed aside.
5
We prefer simple, visible systems over complex plans. A clear calendar, labelled accounts, or gentle reminders can support self control more than detailed spreadsheets.
6
We build around your environment. From payment apps on your phone to conversations at home, we look for small changes that reduce friction for good decisions.
7
We see progress as a series of experiments. You try a new saving or repayment pattern, observe what happens, then we adjust together without judgement.
Meet the team
A small team obsessed with how real people actually behave with money
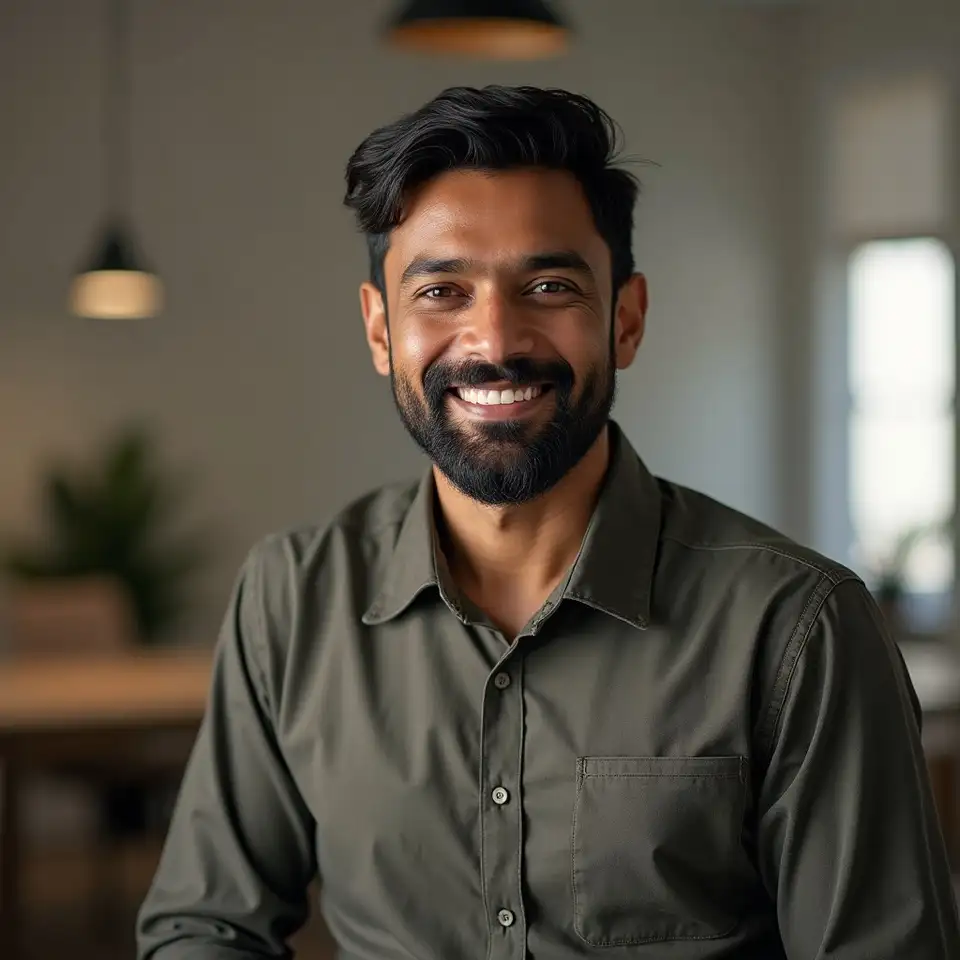
Aarav Shah
Lead behavioral finance specialist
Master level studies in psychology Mumbai based university
Self control in daily money choices
Research led advisory firm
Credentials:
Certificate in behavioral finance practice
Training in habit change and motivational interviewing
Coursework in personal finance regulation India
Workshop on ethical client communication
Approach:
Choice architecture review
Spending trigger analysis
Commitment device design
Debt repayment mapping
Savings pathway planning
Reflective questioning
Values anchored decisions
Key strengths:
Behavioral mapping
Habit design
Client interviewing
Practical planning
Context analysis
Aarav brings a background in behavioral research and years of working with professionals who felt stuck between knowing and doing with money. He translates complex ideas into gentle, practical experiments for daily life.
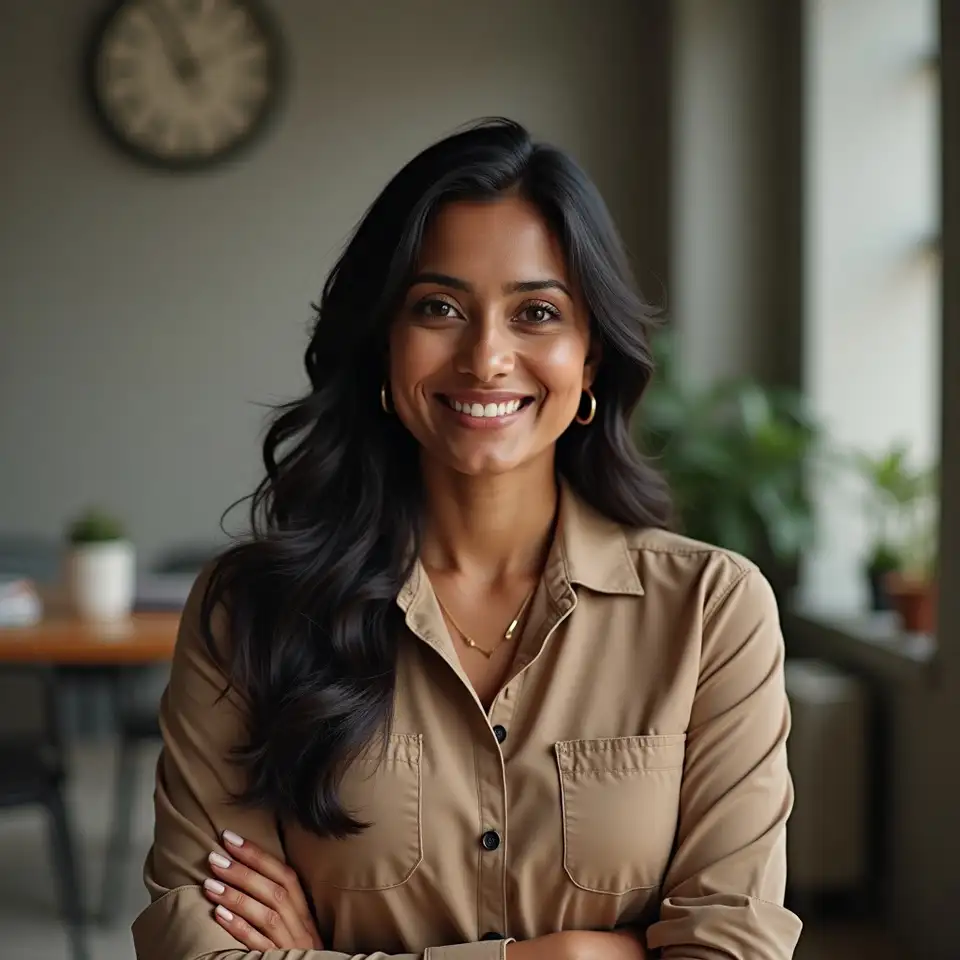
Meera Iyer
Money and emotions specialist
Postgraduate diploma in counselling Delhi based institute
Debt and emotional wellbeing
Community support organisation
Credentials:
Certification in financial counselling skills
Training in behavioural interviewing
Coursework on credit and lending basics
Approach:
Gentle money narrative work
Repayment stress mapping
Supportive accountability check ins
Household rhythm review
Values based spending review
Key strengths:
Active listening
Debt conversation support
Boundary setting
Repayment planning
Family dialogue
Meera focuses on the emotional side of money, helping clients untangle guilt, fear, and pressure around spending and borrowing so that repayment and saving plans feel humane, not harsh.
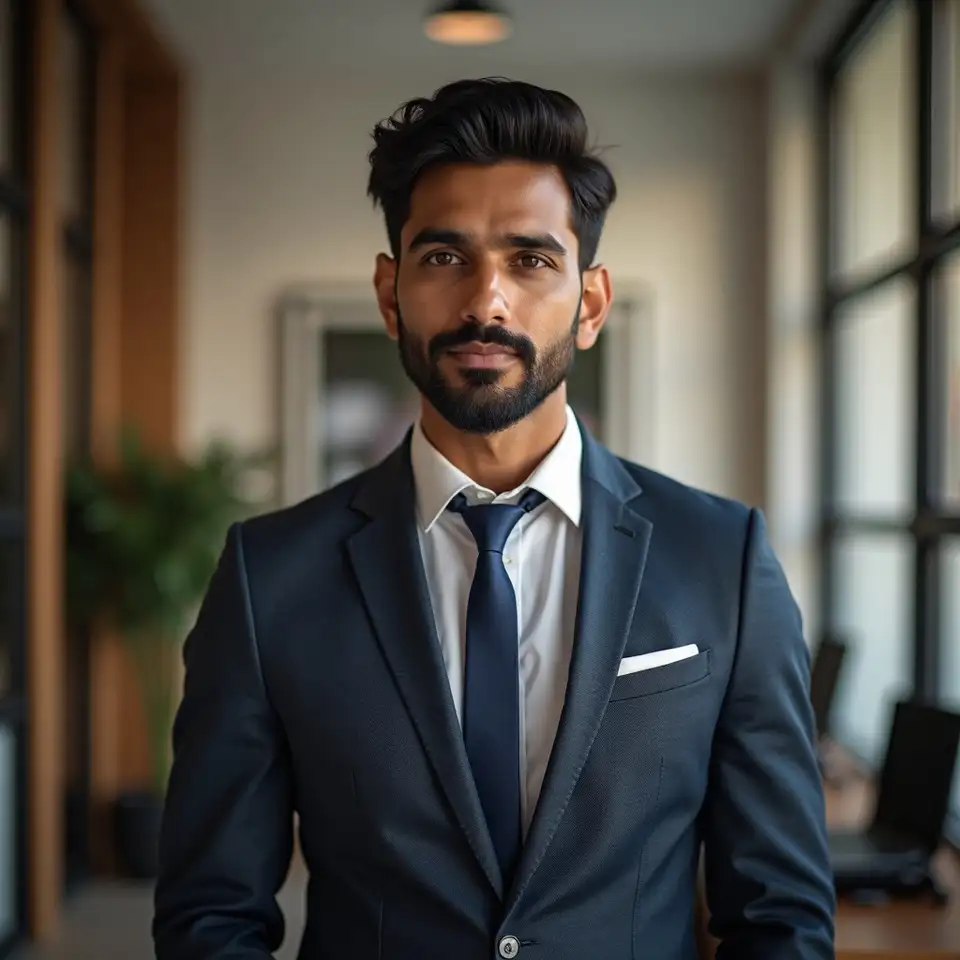
Rahul Deshpande
Behavioural systems lead
Bachelor degree in economics Pune based college
Practical tools for follow through
Fintech operations team
Credentials:
Training in behavioural data analysis
Certification in project management
Workshop on digital privacy and data ethics
Approach:
Plan adherence tracking
Reminder timing experiments
Friction point analysis
Simple dashboard creation
Privacy first data handling
Key strengths:
Data interpretation
System design
Process optimisation
User feedback
Risk awareness
Rahul keeps our tools grounded in real behaviour. He analyses patterns in how clients interact with their plans and reminders, then refines our systems so they fit naturally into everyday routines.
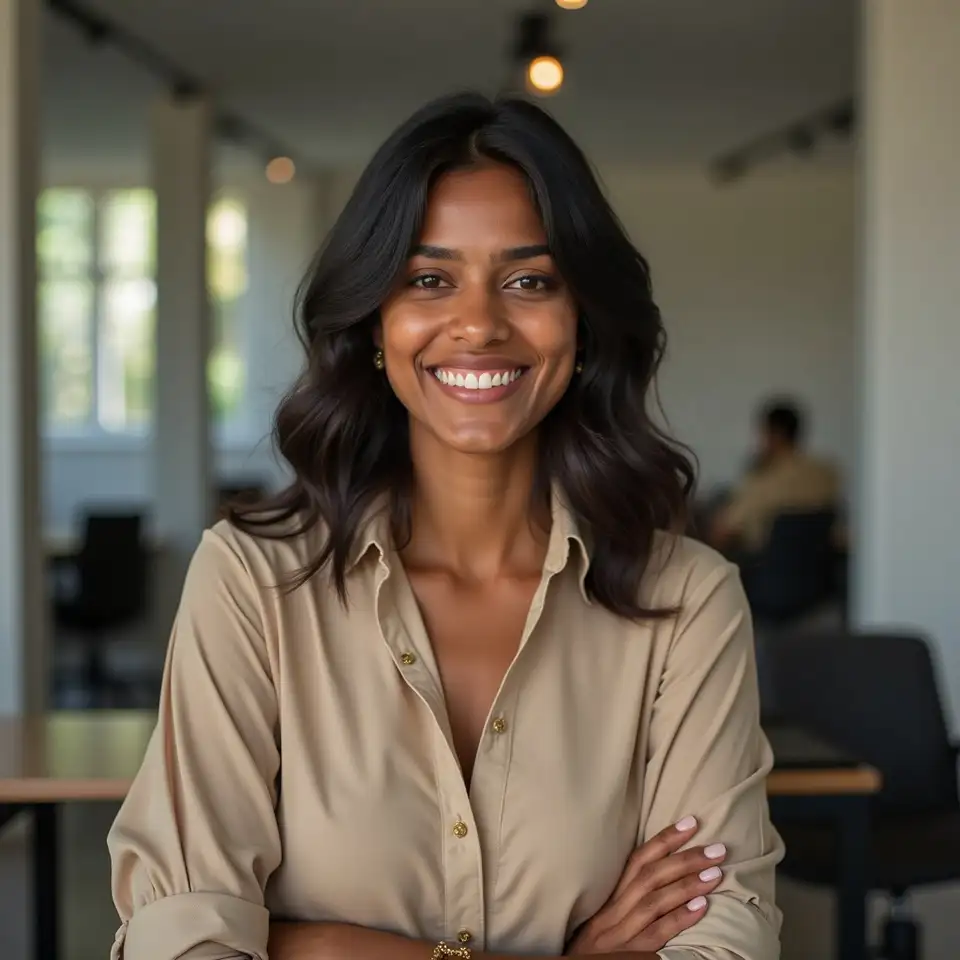
Sana Qureshi
Client experience coordinator
Bachelor degree in business management Bengaluru based college
Client journey and support
Professional services firm
Credentials:
Certification in client service management
Workshop on inclusive communication
Training in confidentiality practices
Approach:
Clear communication templates
Consent centred onboarding
Feedback loop coordination
Service journey mapping
Privacy aware record keeping
Key strengths:
Client support
Process clarity
Expectation setting
Scheduling care
Documentation
Sana is often the first voice you hear from Aimdyaflaepliasoemni. She makes sure your questions are answered, your information is handled with care, and your experience feels calm and organised from start to finish.